Leasehold improvements (LHI) are modifications made to a leased space or leased asset to make it more useful to, or to fit the particular needs of, the tenant. A tenant may want to customize leased office or retail space for their business before moving in. This will likely involve spending money on build-outs or additions to the space (leasehold improvements) to ensure the space meets the tenant’s requirements.
Sometimes, the lessor will reimburse the lessee for leasehold improvements. If a reimbursement or tenant improvement allowance is associated with leasehold improvements made by the lessee, it may be a lease incentive.
Accounting for leasehold improvements can involve both lease accounting and fixed asset accounting. While the lease itself is accounted for under ASC 842, leasehold improvements are generally capitalized and tracked as fixed assets under ASC 360. Understanding how the two interact is important for determining the appropriate useful life, amortization period, tax treatment, and financial statement impact.
Common examples of leasehold improvements
Not every update made to a space can be considered a leasehold improvement. Some improvements, such as those made to the exterior of the building or those that benefit other tenants or the lessor, are not considered leasehold improvements. The criteria to capitalize and record leasehold improvements also depends on any internal capitalization or materiality policy of the company (i.e., tenant), and should be considered when accounting for leasehold improvements.
Here are some common leasehold improvement examples:
- Customized lighting fixtures
- Floor finishes, such as carpet, tile, etc.
- Painting walls or other interior space
- Partitions for separating space
- Addition of a building to leased land
Changes made to the exterior of a building or improvements that benefit other tenants are likely not leasehold improvements. Examples of non-leasehold improvements include things like construction or additions to the elevator, exterior roof, shared parking garage, or any external structural improvements.
To clarify further, increasing the value or the life of an entire property is viewed as a building improvement whereas leasehold improvements are customizations or changes specific to only one tenant.
Accounting for leasehold improvements
Leasehold improvements are assets and are generally included within property, plant, and equipment in the non-current asset section of the balance sheet. As a result, they are accounted for as fixed assets in accordance with ASC 360.
Lease accounting guidance under ASC 842 also impacts how long certain leasehold improvements are amortized because the amortization period may depend on the term of the related lease.
This creates an important connection between an organization’s lease and fixed asset records. The lease contains information such as the lease term, renewal options, and purchase options, while the fixed asset record contains the cost, placed-in-service date, useful life, and depreciation or amortization information associated with the improvement.
Managing leases and fixed assets together can help accounting teams maintain consistency between those records as leases are modified, renewed, terminated, or eventually purchased.
Amortization of leasehold improvements
Under ASC 842-20-35-12, leasehold improvements are generally amortized over the shorter of:
- The useful life of the leasehold improvement, or
- The remaining lease term.
However, if the lease transfers ownership of the underlying asset to the lessee or the lessee is reasonably certain to exercise a purchase option, the leasehold improvements are generally amortized over their useful life.
Determining the appropriate amortization period is important because changes to the lease may also affect the accounting for the related improvement. For example, extending a lease could change the period over which certain leasehold improvements are expected to provide economic benefit.
Example of leasehold improvement amortization
In order to amortize leasehold improvements appropriately, the lessee needs to determine the correct accounting period to apply the amortization rules outlined above.
As an example, let’s assume that a lessee signs a 10 year lease for a building to be used as office space. In addition to the 10 year term, the lessee also has an option to renew the lease for an additional 5 years at the end of the lease term. In order to meet their business needs, the lessee spends $200,000 to customize the offices in the building immediately after the lease commences. The useful life of these improvements (the offices) is 30 years. The lessee decides that, at lease commencement, they are not reasonably certain to exercise the 5 year option to renew the lease. Additionally, there are no purchase options for the office space and ownership does not transfer to the lessee at the end of the lease term.
When the leasehold improvements are made, the lessee makes the following entry:
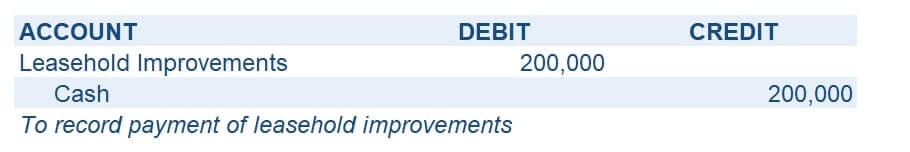
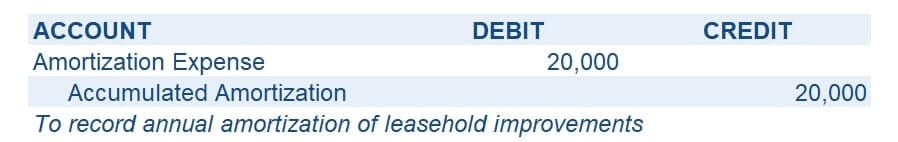
The lessee amortizes the $200,000 cost of the leasehold improvements over the shorter of the useful life of the improvements or the lease term. The lease term is 10 years, and the useful life of the improvements is 30 years, so the $200,000 should be amortized over 10 years.
The lessee will recognize annual amortization expense of 20,000 (200,000/10) over the next 10 years by making the following entry each year:
For organizations managing a larger portfolio of leasehold improvements, manually maintaining these schedules can become difficult, particularly when the underlying leases change. FinQuery allows organizations to manage the lease in LeaseQuery while tracking the related improvement within FinQuery Fixed Assets, helping accounting teams maintain the schedules, journal entries, and supporting records associated with both sides of the transaction.
Leasehold improvements and AROs
Another consideration that must be made when a lessee has leasehold improvements is whether or not an asset retirement obligation (ARO) exists.
An ARO is a liability for the removal of property, equipment, or leasehold improvements at the end of the lease term or retirement of the long-lived asset. ASC 410, Asset Retirement and Environmental Obligations, section 20 (ASC 410-20) contains the guidance from FASB on how to account for AROs. Sometimes the terms of a lease contract require a lessee to remove leasehold improvements they have made to the leased asset prior to returning the asset to the lessor at the end of the lease term. If that is the case, the lessee will record an ARO liability and will need to account for it under ASC 410, in addition to accounting for the leasehold improvements as fixed assets.
For example, assume a lessee enters into a building lease and paints the walls to match their company brand colors. The lease agreement states that the lessee must repaint the walls to their original color. Therefore, the estimated cost to do so is an ARO for the lessee.
It is important to note that both AROs and leasehold improvements do not strictly apply to office space leases, but to all leased assets. An industrial gas production company that leases land and installs underground storage tanks on the site is an example of another ARO scenario. Within the lease terms, the lessor stipulated that the lessee is obligated to restore the site to its original condition prior to when the lessee took control of the leased land. Because the underground storage tanks were installed by the lessee, the lessee’s obligation to remove the tanks is an ARO.
Tax considerations for qualified leasehold improvements
The financial reporting treatment of leasehold improvements and the tax treatment may be very different.
For book purposes, leasehold improvements are generally capitalized and amortized over the appropriate period under US GAAP. For tax purposes, however, certain improvements may qualify for accelerated deductions through Section 179, bonus depreciation, or regular MACRS depreciation.
This can result in an asset having one depreciation schedule for book purposes and a very different schedule for tax purposes.
Qualified improvement property
Qualified improvement property, or QIP, generally includes improvements made to the interior portion of nonresidential real property when the improvement is placed in service after the building itself was first placed in service.
QIP does not include costs attributable to:
- Enlarging the building
- Elevators or escalators
- The building’s internal structural framework
Certain leasehold improvements may meet the definition of QIP, but the terms are not interchangeable. Organizations should evaluate the specific improvement to determine whether it qualifies.
QIP is generally treated as 15-year property for federal tax depreciation purposes, which can also make qualifying property eligible for bonus depreciation.
Section 179 deduction
Section 179 allows businesses to elect to immediately expense some or all of the cost of qualifying property rather than recovering the cost entirely through depreciation over future periods.
Certain qualified real property can be eligible for Section 179, including qualified improvement property and certain improvements to nonresidential real property, such as roofs, HVAC systems, fire protection and alarm systems, and security systems.
For tax years beginning in 2026, the maximum Section 179 deduction is $2.56 million. The deduction begins to phase out when the total cost of Section 179 property placed in service during the year exceeds $4.09 million.
Section 179 is subject to additional requirements and limitations, including a taxable income limitation, so organizations should work with their tax advisors to determine whether an improvement qualifies and how much of the cost should be expensed.
Bonus depreciation
Bonus depreciation is separate from Section 179 and provides another opportunity to accelerate tax depreciation.
Under current federal tax law, certain qualified property acquired and placed in service after January 19, 2025 is generally eligible for 100% bonus depreciation. This includes qualifying property with a MACRS recovery period of 20 years or less, which can include qualified improvement property.
As a result, an improvement that is capitalized and amortized over several years for financial reporting purposes could potentially receive a much larger first-year deduction for tax purposes.
For example, a qualifying leasehold improvement could have:
- Book treatment: Capitalized and amortized over the shorter of its useful life or applicable lease term.
- Tax treatment: Potentially eligible for Section 179, 100% bonus depreciation, or regular MACRS depreciation depending on the facts and circumstances.
These differences make maintaining separate book and tax depreciation schedules especially important.
Tax rules and eligibility requirements can vary based on the specific property and circumstances. Organizations should work with their tax advisors when determining whether leasehold improvements qualify for Section 179, bonus depreciation, or other tax treatment.
Managing the lease and the leasehold improvement together
Leasehold improvements are a good example of where lease accounting and fixed asset accounting overlap.
The underlying lease may need to be accounted for under ASC 842, while the improvement itself is tracked as a fixed asset under ASC 360. The accounting team may also need separate book and tax depreciation schedules for the improvement.
Managing each of these pieces in separate spreadsheets can make it harder to keep information aligned, particularly when there are changes to the lease or the asset.
With FinQuery, organizations can manage both sides of the process within the same platform.
LeaseQuery helps organizations manage the underlying lease, including lease terms, amendments, remeasurements, amortization schedules, journal entries, and reporting required under ASC 842.
FinQuery Fixed Assets helps organizations manage the leasehold improvement throughout its fixed asset lifecycle, including capitalization, depreciation, book and tax treatment, journal entries, disposals, and reporting.
Bringing lease and fixed asset accounting together in one platform gives accounting teams greater visibility into both leased and owned assets while reducing the need to maintain separate manual schedules.
Summary
Understanding what qualifies as a leasehold improvement is the first step in applying the appropriate accounting treatment.
For financial reporting purposes, leasehold improvements are generally recorded as fixed assets and amortized over the shorter of their useful life or the applicable lease term, unless ownership transfers or a purchase option is reasonably certain to be exercised.
Certain improvements may qualify as QIP and could be eligible for Section 179 or bonus depreciation. For 2026, the Section 179 deduction limit is $2.56 million, subject to the applicable phaseout and other limitations. Eligible qualified property acquired and placed in service after January 19, 2025 may also qualify for 100% bonus depreciation.
Because the same improvement can have different lease, book, and tax considerations, keeping those records connected is increasingly important. LeaseQuery and FinQuery Fixed Assets can help accounting teams manage the underlying lease and related fixed assets in one platform, automate the associated schedules and journal entries, and maintain the supporting records needed for reporting and audit.