A revolving line of credit allows a business to borrow, repay, and borrow again within an agreed limit, subject to its lending agreement. Often called a “revolver”, it commonly supports working capital needs, including inventory purchases, payroll, and payments to suppliers.
Under US GAAP, accounting for a revolving line of credit involves recording outstanding borrowings, recognizing interest and fees, determining current or noncurrent classification, and presenting the related disclosures.
How a revolving line of credit works
The lending agreement specifies the credit limit, maturity date, interest rate, repayment requirements, and any collateral or financial covenants. Repaying principal generally restores borrowing capacity, provided the borrower continues to meet the agreement’s conditions.
The stated credit limit may differ from the amount available to borrow. Availability can be reduced by outstanding borrowings, letters of credit, or restrictions based on eligible accounts receivable and inventory.
For example, a business with a $500,000 line of credit draws $150,000. Assuming no other restrictions, it has $350,000 available. A subsequent $50,000 principal repayment reduces outstanding debt to $100,000 and increases available capacity to $400,000.
Revolving lines of credit typically have a maturity or renewal date. The ability to borrow again does not remove the obligation to repay amounts when due.
Recording borrowings and repayments
The business recognizes a borrowing liability when it draws funds. The instrument limit is not itself a liability, and unused borrowing capacity is not recorded as cash or another asset.
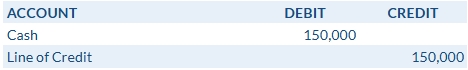
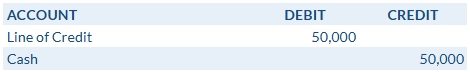
For a straightforward borrowing at face value, excluding fees and other adjustments, the entries for a $150,000 draw and $50,000 repayment are as follows:
DRAW
REPAYMENT
Borrowing proceeds are not revenue, and principal repayments are not expenses. Both transactions affect the balance sheet without directly affecting net income.
Recognizing interest expense
Interest is accrued as incurred, rather than only when paid. The calculation should reflect outstanding principal, the contractual interest rate, rate changes, and the agreement’s day count convention.
Using only the month end balance can misstate interest when borrowings and repayments occur throughout the month.
Assume a business has $100,000 outstanding for 30 days at an annual interest rate of 6%, using a 360 day year:
$100,000 × 6% × 30 ÷ 360 = $500
The entry recorded for interest expense is:
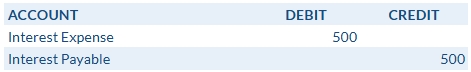
When the interest is paid, the business debits interest payable and credits cash. This example assumes the interest does not qualify for capitalization under ASC 835-20.
Accounting for instrument fees and issuance costs
Revolving instruments may involve upfront financing costs, ongoing commitment fees, and administrative charges. These amounts should be evaluated according to their purpose and the period they relate to.
For line of credit agreements, guidance within ASC 835-30 allows debt issuance costs to be deferred as an asset and amortized over the instrument’s term. This treatment applies regardless of whether the borrower has an outstanding balance.
For example, qualifying issuance costs of $12,000 for a three year instrument would result in monthly amortization of approximately $333 under this approach. Repaying all outstanding principal does not require the remaining deferred costs to be written off if the line of credit remains available.
Recurring commitment fees for maintaining unused borrowing capacity are generally recognized over the period the lender provides that availability. Accountants should distinguish these charges from upfront issuance costs and separately evaluate the effects of amendments, renewals, or early termination.
Classifying the liability as current or noncurrent
Borrowings due within one year of the balance sheet date are generally current liabilities unless an applicable exception is satisfied.
A multiyear agreement does not automatically support noncurrent classification. The assessment must consider the repayment terms of outstanding draws, demand provisions, covenant violations, and any arrangements requiring customer receipts to be applied against the debt.
Debt that becomes callable because of a covenant violation is generally current. A qualifying lender waiver obtained before the financial statements are issued – or available to be issued – may support noncurrent classification. The assessment also considers the waiver’s duration and whether future violations of the same or more restrictive covenants are probable.
The accounting team should document its classification conclusion using the executed agreement and any amendments or waivers.
Period-end accounting and disclosures
The borrowing schedule should reconcile opening principal, additional draws, repayments, and other movements to the ending general ledger balance. Accrued interest and deferred issuance costs should be tracked separately.
At each reporting date, the accounting team should:
- Reconcile outstanding principal to lender records
- Verify interest accruals and fee amortization
- Review covenant compliance and any lender waivers
- Reassess current and noncurrent classification
- Evaluate amendments, renewals, and termination provisions
- Prepare applicable disclosures about borrowing terms, maturities, collateral, restrictions, and defaults
These procedures help ensure that the financial statements accurately present the outstanding obligation, the cost of borrowing, and material conditions affecting the instrument.